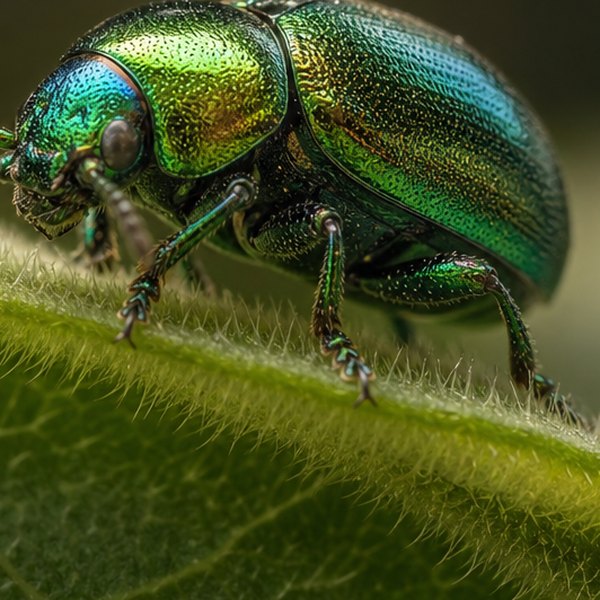
It’s in Alabama in 1915 that a small grey insect about the size of a pea is quietly eating its way through the future of British homeownership. The insect was a weevil: it had a snout, a modest appetite, and absolutely no interest in the long-term consequences of its lunch.
The consequences were enormous. If you ever signed an offer on a mortgage with a two-year fixed rate and a slightly dazed expression, then you are living with them in a small but genuinely traceable way.
The Insect That Broke the American South
The boll weevil crossed into the United States from Mexico in the 1890s and, over the next two decades, travelled from county to county in the cotton belt. When it reached the deep south in full force, the boll weevil was not just eating cotton plants – it was collapsing entire regional economies.
The farmers who had borrowed against future harvests suddenly had no harvest. The banks that had lent against cotton land now found themselves holding collateral worth a fraction of what it had been. The agricultural credit system built on the assumption that cotton would keep growing came apart very quickly.
This created an immediate and desperate problem for American lenders: how do you lend money against land when the land's income is suddenly unreliable? The old model – short-term loans, rolled over repeatedly, dependent on the borrower's annual yield – simply didn't work anymore.
The Emergency Fix That Became the Blueprint
American banks and federal lending programmes, responding to the further shocks of the Depression years, moved away from short lending periods tied to harvests and established lending with longer, fixed terms. In place of variable payments that moved with whatever the market was doing, the borrower paid a fixed amount each month spread across years. The borrower knew exactly what they owed and when, and the lender had predictable, steady repayments instead of a lump sum they might never see.
In other words, the fixed-rate mortgage was partly a workaround — designed to make lending feel safe in a landscape that had just demonstrated, very dramatically, that it wasn't.
Those structures, refined through the mid-twentieth century and exported through American financial influence across the Atlantic, became the template that British lenders eventually adopted and adapted. The point here is the instrument itself – and where it actually came from.
What You're Really Signing
A two or five year fixed-rate period is the direct descendant of those emergency lending structures. Both parties get certainty for a defined period, then things can be reassessed.
Lenders are using a tool here that was designed, under genuine economic pressure, to make the whole system stable enough to keep functioning. It is not a favour that the lender is doing you. That's not cynicism. It's just useful to know, because it changes how you think about the choice.
A two-year fix is not some ‘safe option’ in some abstract sense. A two-year fix is a specific trade. You are paying a rate that is often slightly higher than the cheapest variable deal available, in exchange for knowing exactly what you will pay for the next 24 months. The lender is taking the risk that rates will go up above what they have charged you. You are taking the risk that rates will fall and you’ll be locked out of the benefit.
The Snout That Reshaped the Spreadsheet
The boll weevil is still a regulated pest in parts of the American south. The town of Enterprise, Alabama even has a boll weevil monument, erected in 1919. The crop failures caused by the boll weevil forced local farmers to diversify into peanuts and other crops, which ultimately made the region more economically resilient than it had been when everything depended on cotton.
Sometimes the thing that breaks a system is the thing that quietly improves it. A fixed-rate mortgage might be the most widespread example of that idea in modern life, sitting there in a folder of paperwork that most people read once and never look at again.
Questions this raises
- Why are British mortgages usually fixed for only two years?
- How did American farming change UK home lending?
- Is a two-year fix better than a five-year one?
- What happens when a fixed mortgage rate ends?